Want to Build Wealth? Buy a Home This Year.

Want to Build Wealth? Buy a Home This Year. | MyKCM
Every year, households across the country make the decision to rent for another year or take the leap into homeownership. They look at their earnings and savings and then decide what makes the most financial sense. That equation will most likely take into consideration monthly housing costs, tax advantages, and other incremental expenses. Using these measurements, recent studies show that it’s still more affordable to own than rent in most of the country.

There is, however, another financial advantage to owning a home that’s often forgotten in the analysis – the wealth built through equity when you own a home.

Odeta Kushi, Deputy Chief Economist for First American, discusses this point in a recent blog post. She explains:

“Once you include the equity benefit of price appreciation, owning made more financial sense than renting in 48 out of the 50 top markets, with the only exceptions being San Francisco and San Jose, Calif.”

What has this equity piece meant to homeowners in the past?

ATTOM Data Solutions, the curator of one of the nation’s premier property databases, just analyzed the typical home-price gain owners nationwide enjoyed when they sold their homes. Here’s a breakdown of their findings:Want to Build Wealth? Buy a Home This Year. | MyKCMThe typical gain in the sale of the home (equity) has increased significantly over the last five years.

CoreLogic, another property data curator, also weighed in on the subject. According to their latest Homeowner Equity Insights Report, the average homeowner gained $17,000 in equity in just the last year alone.

What does the future look like for homeowners when it comes to equity?

Here are the seven major home price appreciation forecasts for 2021:Want to Build Wealth? Buy a Home This Year. | MyKCMThe National Association of Realtors (NAR) just reported that today, the median-priced home in the country sells for $309,800. If homes appreciate by 5% this year (the average of the forecasts), the homeowner will increase their wealth by $15,490 in 2021 through increased equity.

Bottom Line

As you make your plans for the coming year, be sure to consider the equity benefits of home price appreciation as you weigh the financial advantages of buying over renting. When you do, you may find this is the perfect time to jump into homeownership.
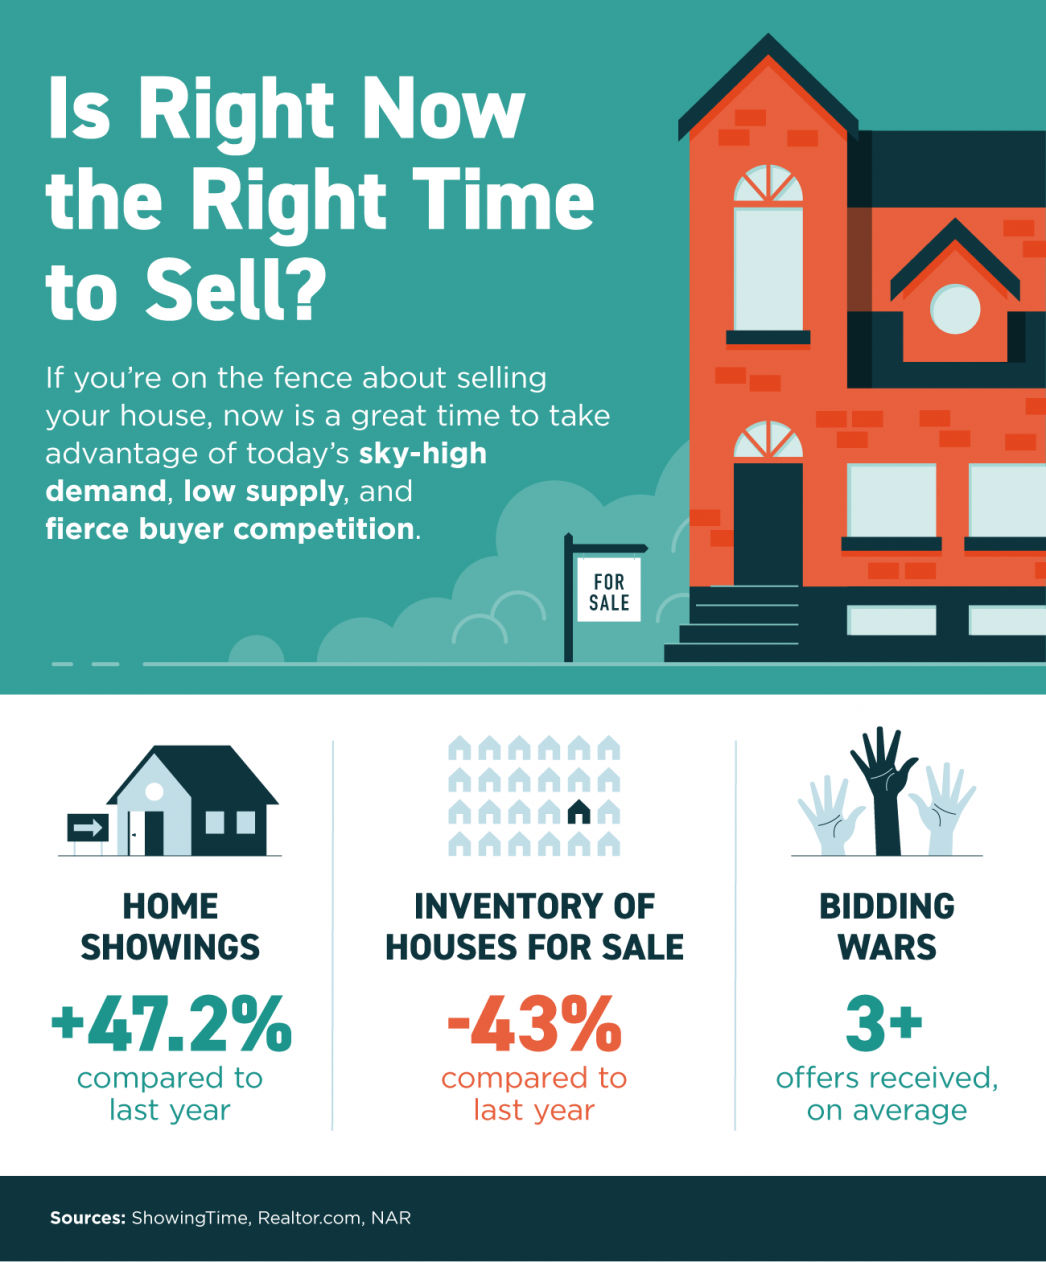
Is Right Now the Right Time to Sell? [INFOGRAPHIC]

Is Right Now the Right Time to Sell? [INFOGRAPHIC] | MyKCM

Some Highlights

  • If you’re on the fence about selling your house, now is a great time to take advantage of sky-high demand, low supply, and fierce buyer competition.
  • With buyer demand rising and historically low inventory for sale, if you’re in a position to move, your house may really stand out from the crowd.
  • Let’s connect today to get your listing process underway.

How to Make the Dream of Homeownership a Reality This Year

How to Make the Dream of Homeownership a Reality This Year | MyKCM

In 1963, Martin Luther King, Jr. inspired a powerful movement with his famous “I Have a Dream” speech. Through his passion and determination, he sparked interest, ambition, and courage in his audience. Today, reflecting on his message encourages many of us to think about our own dreams, goals, beliefs, and aspirations. For many Americans, one of those common goals is owning a home: a piece of land, a roof over our heads, and a place where we can grow and flourish.

If you’re dreaming of buying a home this year, start by connecting with a local real estate professional to understand what goes into the process. With a trusted advisor at your side, you can then begin to answer the questions below to set yourself up for homebuying success.

1. How Can I Better Understand the Process, and How Much Can I Afford?

The process of buying a home is not one to enter into lightly. You need to decide on key things like how long you plan on living in an area, school districts you prefer, what kind of commute works for you, and how much you can afford to spend.

Keep in mind, before you start the process to purchase a home, you’ll also need to apply for a mortgage. Lenders will evaluate several factors connected to your financial track record, one of which is your credit history. They’ll want to see how well you’ve been able to minimize past debts, so make sure you’ve been paying your student loans, credit cards, and car loans on time. If your financial situation has changed recently, be sure to discuss that with your lender as well. Most agents have loan officers they trust and will provide referrals for you.

According to ConsumerReports.org:

“Financial planners recommend limiting the amount you spend on housing to 25 percent of your monthly budget.”

2. How Much Do I Need for a Down Payment?

In addition to knowing how much you can afford on a monthly mortgage payment, understanding how much you’ll need for a down payment is another critical step. Thankfully, there are many different options and resources in the market to potentially reduce the amount you may think you need to put down.

If you’re concerned about saving for a down payment, start small and be consistent. A little bit each month goes a long way. Jumpstart your savings by automatically adding a portion of your monthly paycheck into a separate savings account or house fund. AmericaSaves.org says:

“Over time, these automatic deposits add up. For example, $50 a month accumulates to $600 a year and $3,000 after five years, plus interest that has compounded.”

Before you know it, you’ll have enough for a down payment if you’re disciplined and thoughtful about your process.

3. Saving Takes Time: Practice Living on a Budget

As tempting as it is to pass the extra time you may be spending at home these days with a little retail therapy, putting that extra money toward your down payment will help accelerate your path to homeownership. It’s the little things that count, so start trying to live on a slightly tighter budget if you aren’t doing so already. A budget will allow you to save more for your down payment and help you pay down other debts to improve your credit score.

A survey of millennial spending shows, “68% reported that shelter in place orders helped them save for their down payment.” Danielle Hale, Chief Economist at realtor.com, also notes:

“If there is any silver lining to the current economic landscape, it’s that mortgage rates are hanging around record lows…Additionally, shelter-in-place orders helped many who were fortunate enough to keep their jobs save for a down payment — one of the largest hurdles of buying a home. The combination of low rates and the opportunity to save is enabling many millennials to move up their home buying timeline.”

While you don’t need to cut all of the extras out of your current lifestyle, making smarter choices and limiting your spending in areas where you can slim down will make a big difference.

Bottom Line

If homeownership is on your dream list this year, take a good look at what you can prioritize to help you get there. To determine the steps you should take to start the process, let’s connect today.